 Contact
 Help






Shanghai Gold Exchange (SGE)


The Shanghai Gold Exchange (SGE, 上海黄金交易所) is China’s national gold exchange and the centre of the world’s largest physical gold market. Opened in October 2002 under the supervision of the People’s Bank of China, it is where China’s banks, refiners, jewellers and investors buy and sell gold. Unlike London or New York, its trading is closely tied to physical metal held in the exchange’s own vaults.
That design makes the SGE quite different from the two markets that dominate gold pricing in the West. The London Bullion Market Association oversees an over-the-counter market where most trades settle in unallocated gold that never moves. COMEX is a futures exchange where few contracts ever end in delivery. The SGE sits at the physical end of the spectrum. Gold that enters China’s wholesale market is traded through it, and gold that leaves its vaults is generally on its way to jewellery workshops, bar and coin buyers, or industry. That is why SGE data is watched so closely as a signal of Chinese demand.
Since 2016 the SGE has also set its own yuan-denominated benchmark, the Shanghai Gold Benchmark Price, which challenges London’s long-standing role in setting the world price of gold. Through its International Board, and since 2025 a certified vault in Hong Kong, it has begun opening China’s gold market to foreign participants on its own terms.
This guide covers what the SGE is and how it works, its contracts and vault network, how to read its withdrawal figures, the Shanghai benchmark price, the International Board, and what the price gap between Shanghai and London tells you about gold demand. For the wider picture of how gold flows into and around China, see our guide to the Chinese gold market.
Highlights
- The Shanghai Gold Exchange (SGE) is China’s national precious metals exchange, opened in 2002 under the supervision of the People’s Bank of China.
- It is the world’s largest exchange for physical gold delivery. Contracts are paid in full, priced in yuan per gram, and settled from SGE-certified vaults.
- Gold withdrawn from SGE vaults is widely used as a measure of Chinese wholesale gold demand.
- The Shanghai Gold Benchmark Price, launched in 2016, is set twice daily in yuan for 1 kg bars of 99.99% purity.
- The SGE International Board lets foreign institutions trade, but individual foreign investors can’t open accounts.
- The gap between Shanghai and London gold prices is a closely watched signal of Chinese demand, because China tightly controls gold imports and exports.
What Is the Shanghai Gold Exchange?
The Shanghai Gold Exchange is China’s national exchange for gold, silver and platinum. It was established by the People’s Bank of China (PBoC) in October 2002 with approval from the State Council, and it remains under the central bank’s supervision. The PBoC nominates its senior management. It is a non-profit, membership-based organisation, headquartered in Shanghai, and it publishes prices, data and announcements on its website, sge.com.cn, with an English version at en.sge.com.cn.
Before 2002, gold in China was bought and sold at fixed prices through the PBoC, and private ownership was tightly restricted. The SGE was created to replace that system with a market, and it is now the foundation of the whole Chinese gold trade. Chinese rules channel newly refined and imported gold into the wholesale market through the SGE. As a result, almost every bar that reaches a Chinese jeweller, bank or investor has passed through its trading system and vaults.
SGE Members
Only members can trade on the SGE directly. Everyone else, from jewellery companies to individual investors, trades through a member, usually one of the large state-owned banks. At the end of 2024 the exchange had 300 members and around 14,400 corporate clients, with millions of individual investors trading through member banks.
| Member category | Number (end 2024) | Who they are |
|---|---|---|
| Ordinary members | 146 | Chinese banks, refiners, miners and jewellery manufacturers |
| International members | 104 | Foreign banks, refiners and trading firms, trading through the International Board |
| Other special members | 50 | Foreign bank branches in China, securities firms, trust companies and smaller banks |
Among the international members are many of the names that also dominate London and New York, including global bullion banks and Swiss refiners. They access the market through the SGE’s International Board, covered later in this guide.
How Big Is the SGE?
By volume, the SGE is one of the world’s busiest gold markets. In 2024 it traded 62,300 tonnes of gold, worth RMB 34.65 trillion, along with 158,000 tonnes of silver and 100 tonnes of platinum. Those totals count each trade, including deferred contracts that roll over without delivery, so they say more about trading activity than about physical metal.
Its real distinction is delivery. The exchange runs a network of 69 certified vaults in 37 locations across China, and a large share of the gold traded on it is withdrawn as physical metal. In 2025, 1,298 tonnes of gold were withdrawn from SGE vaults. That is more than a third of the world’s annual mine production, and it makes the SGE the largest exchange in the world for physical gold delivery.
How the SGE Works: Contracts and Delivery
The SGE works differently from most commodity exchanges. On its main contracts, a buyer must have the full purchase price in their account before placing an order, and a seller must already hold the gold in an SGE vault. There is no leverage and no selling metal you don’t have. When a trade is matched, ownership of gold in the exchange’s vaults simply moves from seller to buyer. Gold can stay in the vault indefinitely and change hands many times, or it can be withdrawn as physical bars.
The Main Contracts
The SGE lists contracts for gold, silver and platinum. The most important contracts trade in standard bars of set weights and purities, held in SGE-certified vaults.
| Contract | Metal | Standard bar | Type |
|---|---|---|---|
| Au99.99 | Gold | 1 kg, 99.99% | Spot, full payment |
| Au99.95 | Gold | 3 kg, 99.95% | Spot, full payment |
| Au99.5 | Gold | 12.5 kg, 99.5% (London Good Delivery size) | Spot, full payment |
| Au100g | Gold | 100 g, 99.99% | Spot, full payment |
| Au(T+D) | Gold | Deliverable in 1 kg and 3 kg bars | Deferred, with margin |
| mAu(T+D) | Gold | Smaller lots of the Au(T+D) contract | Deferred, with margin |
| Ag(T+D) | Silver | Deliverable in silver bars | Deferred, with margin |
| Pt99.95 | Platinum | 1 kg, 99.95% | Spot, full payment |
The spot contracts, led by Au99.99, are the physical heart of the exchange. The deferred contracts, known as T+D, work more like futures. Traders post a margin rather than the full price, and positions roll over from day to day until the holder closes them or asks for delivery. The deferred contracts account for much of the exchange’s trading volume, but delivery from them is optional.
Most of this is invisible to the end buyer. Alongside the exchange’s order book, members also trade with each other directly in an over-the-counter “price inquiry” market, which includes forwards and swaps. Banks also lend gold to jewellery manufacturers through the SGE. These wholesale functions matter to China’s banks, but a private investor will only ever meet them indirectly, through the prices their bank or dealer quotes.
Vaults and Withdrawals
All metal traded on the SGE sits in its network of certified vaults, run mainly by China’s large state banks. Gold enters those vaults from domestic refiners and through imports. It leaves when a member withdraws it, usually to make jewellery, to supply bars and coins to banks and retailers, or for industrial use. The amount withdrawn each month is published and is the most closely watched number the SGE produces.
Inside the system, gold trades free of value-added tax. VAT applies once gold leaves it for most purposes other than investment, as our guide to China’s gold VAT system explains. That gives Chinese gold a strong reason to pass through the exchange.
Why SGE Withdrawals Are Read as Chinese Demand
Because new gold in China has to pass through the SGE, withdrawals are widely used as a measure of Chinese wholesale demand. The World Gold Council now uses them in exactly that way in its monthly China reports. In 2025, withdrawals totalled 1,298 tonnes. That was 11% less than in 2024 and 28% below the ten-year average, as high prices cooled jewellery buying.
The figure is often misread, though, because withdrawals are not the same as consumption. Recycled gold that has been melted down and re-refined goes back into SGE vaults and can be withdrawn a second time. Withdrawals also include metal taken out for stockpiling. They are therefore usually much higher than estimates of Chinese consumer demand. In 2013, the year of China’s great gold-buying boom, SGE withdrawals were close to 2,200 tonnes, more than twice the WGC’s estimate of Chinese consumer demand for the same year.
BullionStar has long argued that the gap points to more gold flowing into China than the WGC’s demand figures capture. Read carefully, withdrawals are the best available measure of how much physical gold China’s wholesale market absorbs. They are not a precise count of what Chinese households buy.
The Shanghai Gold Benchmark Price
Since 19 April 2016 the SGE has set its own benchmark gold price, the Shanghai Gold Benchmark Price, known in China as “Shanghai Gold” (上海金). It was China’s first yuan-denominated gold benchmark, created so that the world’s largest physical gold market would no longer have to take its reference price from London.
How the Shanghai Benchmark Is Set
The benchmark is set twice each trading day, at 10:15am and 2:15pm Beijing time, in an electronic auction on the SGE’s platform. Participants bid and offer for 1 kg bars of 99.99% gold, with the price quoted in yuan per gram. The auction runs in rounds, and the price is adjusted until buying and selling are close to balanced. The final price becomes the Shanghai benchmark for that session, published as the morning (SHAU AM) and afternoon (SHAU PM) price.
The auction is open to a set group of participants: mostly China’s large state banks, alongside foreign banks with Chinese operations, gold producers and jewellers. Unlike London’s auction, every trade is centrally cleared by the exchange and settled in physical gold held in SGE vaults.
How It Differs from the LBMA Gold Price
| Shanghai Gold Benchmark Price | LBMA Gold Price | |
|---|---|---|
| Where it is set | Shanghai Gold Exchange | London, run by ICE Benchmark Administration |
| Currency and unit | Chinese yuan per gram | US dollars per troy ounce |
| Gold traded | 1 kg bars, 99.99% pure | 400 oz bars, at least 99.5% pure |
| Settlement | Physical gold in SGE vaults, centrally cleared | Unallocated gold, settled between banks |
| Times | 10:15am and 2:15pm Beijing time | 10:30am and 3pm London time |
The two prices rarely match exactly once converted into the same currency and unit. The difference between them, the Shanghai premium or discount, is covered later in this guide.
Finding the Shanghai Gold Price
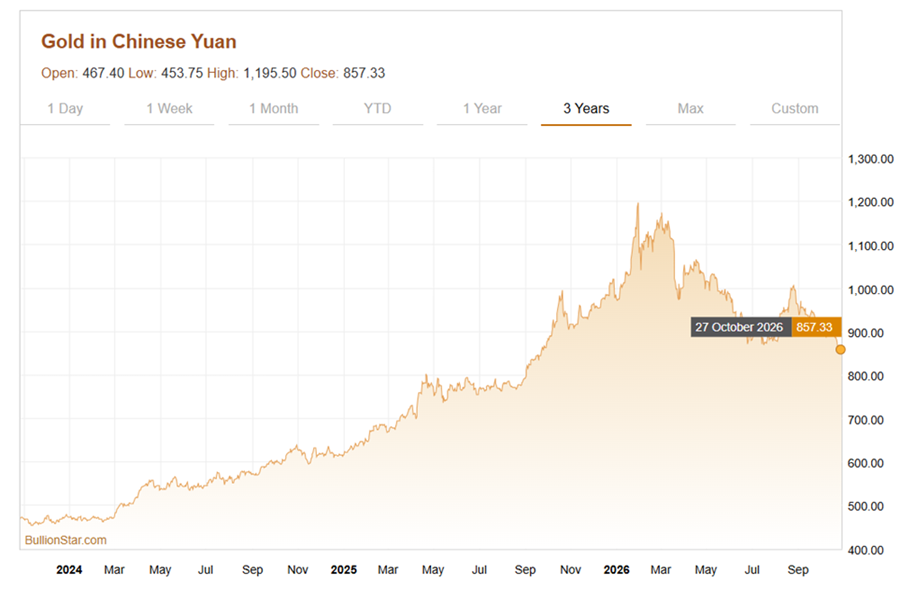
The SGE publishes its benchmark and live contract prices on its website. Our gold price page shows the latest Shanghai Gold Benchmark Price alongside the LBMA Gold Price, per troy ounce and in a range of currencies, so you can compare the two directly. Its live chart can also be set to Chinese yuan per gram, the unit the SGE uses.
The SGE International Board (SGEI)
The Shanghai Gold Exchange International Board, usually shortened to SGEI, is the SGE’s route for foreign participation. It launched in September 2014 as a wholly owned SGE subsidiary, registered in the China (Shanghai) Pilot Free Trade Zone with capital of RMB 2 billion.
The free trade zone matters because, for customs purposes, it is treated as outside mainland China. Gold held in an SGEI vault in the zone is not subject to China’s import and export controls. Foreign banks, refiners and trading firms can therefore buy and sell gold on the SGE exchange system without bringing metal into the domestic market. The SGEI’s main contracts mirror the domestic ones: iAu99.99 (1 kg), iAu99.5 (12.5 kg bars) and iAu100g. All of them are priced in yuan and settled through special free trade accounts.
China had two clear aims in creating the SGEI. The first was to promote the yuan, and the “Shanghai gold” price, as an international reference for gold. The second was to give foreign gold an open channel into the Chinese market. Its international members now include major global bullion banks and Swiss refiners, and the SGE reported 104 international members at the end of 2024. In 2015 the SGE also set up a “Gold Connect” link with Hong Kong’s Chinese Gold and Silver Exchange Society.
In June 2025 the SGE opened its first certified vault outside mainland China, in Hong Kong, with International Board contracts for delivery there. This brings SGE-standard trading and storage to a financial centre that foreign participants can access more easily. It also puts Shanghai in direct competition with London and Singapore for Asian vaulting business.
Even so, the International Board has not reshaped global pricing in the way some expected. London and New York still dominate trading in international gold, and most SGE volume remains domestic. We look at this in more detail in What Happened to the Shanghai International Gold Exchange?
Individual foreign investors also cannot open accounts on the SGEI. Access is through members, and those members are institutions. For a closer look at how the board’s vaults, accounts and contracts work, see our guide to the mechanics of the Shanghai International Gold Exchange.
What the SGE Means for Gold Prices Globally
China is the world’s largest gold producer and its largest consumer, so the price of Shanghai gold can tell you a lot about global demand. The SGE doesn’t set the international gold price. Most of that price discovery still happens in London’s over-the-counter market and on COMEX futures in New York. But Shanghai is where much of the world’s physical demand shows up first, and the gap between Shanghai and Western prices is one of the most closely watched signals in the gold market.
The Shanghai-London Premium
The SGE quotes gold in yuan per gram, while London quotes in US dollars per troy ounce. To compare them, convert the Shanghai price into dollars per ounce. Multiply the yuan-per-gram price by 31.1035 (the number of grams in a troy ounce) and divide by the dollar–yuan exchange rate. The difference between that figure and the London price is the Shanghai premium, or discount.
In most markets, a gap like this would be closed quickly by traders buying in the cheaper market and selling in the dearer one. China’s gold market doesn’t work that way. Gold can only be imported by a small number of banks with licences from the People’s Bank of China, and exports of gold are tightly restricted. Metal flows into China far more easily than it flows out. As a result, a premium can last for weeks or months.
A rising premium usually means Chinese buyers are paying up for gold faster than imports can arrive. That can come from strong jewellery, bar and coin demand, or from the PBoC slowing import quotas. Premiums jumped sharply in late 2023 when import quotas tightened while domestic demand was strong. A discount usually means demand inside China is weak relative to supply, and buyers can wait for lower prices.
Shanghai’s Growing Influence
Shanghai’s role in setting prices has grown since the Shanghai Gold Benchmark Price launched in 2016. The SGE also runs night trading sessions that overlap with European and US hours. Large moves in Shanghai during Asian trading can now carry through into London and New York when they open, especially when Chinese investment demand is strong.
Gold that Shanghai’s buyers take in rarely comes back. Because gold does not easily leave China, metal withdrawn from SGE vaults is effectively removed from the global supply available to Western markets. This one-way flow is a large part of why analysts follow SGE withdrawals and the Shanghai premium together. For more on how the domestic market fits together, see our guide to the Chinese gold market.
The People’s Bank of China’s Gold Reserves
The People’s Bank of China (PBoC), which supervises the SGE, is also one of the world’s largest official holders of gold. It reported 77.47 million troy ounces (about 2,410 tonnes) as of the end of September 2026. September was its 23rd consecutive month of reported purchases.
The PBoC is generally thought to buy its gold outside the SGE, on international markets, so its purchases are unlikely to show up in SGE withdrawals. Its reporting has also been patchy. There have been long gaps between disclosures, after which large increases were reported at once, such as between 2009 and 2015. For that reason, many market watchers believe China’s true gold holdings are well above the official figure.
Either way, state and private buying together make China one of the largest sources of demand that does not return gold to Western markets. We cover the PBoC’s reserve history and reporting in more detail in our guide to China’s gold reserves.
Frequently Asked Questions
What is the Shanghai Gold Exchange?
The Shanghai Gold Exchange (SGE) is China’s national exchange for gold, silver and platinum. It opened in October 2002 under the supervision of the People’s Bank of China. Trading is in yuan, contracts are paid for in full, and they can be settled with physical metal from SGE-certified vaults. By the volume of gold it delivers, it is the largest physical gold exchange in the world.
How is the SGE different from COMEX and the LBMA?
The SGE is a physical gold exchange: buyers pay in full and can take delivery of bars from its vaults. The LBMA oversees London’s over-the-counter market, where banks trade with each other directly, mostly in unallocated gold, and prices are quoted in US dollars per troy ounce. COMEX is a futures exchange in New York, where most contracts are closed out before delivery. The SGE prices gold in yuan per gram and serves mainly China’s domestic market.
What are SGE withdrawals and why do they matter?
SGE withdrawals are the amount of gold that members and clients physically take out of the exchange’s vaults. China’s newly mined and imported gold mostly passes through the SGE, so withdrawals are widely used as a measure of Chinese wholesale gold demand. SGE withdrawals were 1,298 tonnes in 2025. They usually run higher than consumer demand estimates because they also include recycled gold and gold used by industry.
What is the Shanghai gold benchmark price?
The Shanghai Gold Benchmark Price is the SGE’s official yuan gold price. It launched in April 2016 and is set twice each trading day, at 10:15am and 2:15pm Beijing time. Prices are set through auction rounds, quoted in yuan per gram for 1 kg bars of 99.99% purity. Trades at the benchmark are settled with physical gold.
Can foreigners trade on the SGE?
Individual foreign investors can’t open an account on the SGE gold exchange. Foreign banks, refiners and trading firms can trade through the SGE International Board (SGEI) as international members. The SGEI has vaults in the Shanghai Free Trade Zone and, since June 2025, in Hong Kong. Some foreign banks also take part through their Chinese subsidiaries as domestic members.
What is the Shanghai-London gold premium?
The Shanghai-London gold premium is the difference between the SGE gold price, converted to US dollars per troy ounce, and the London price. A premium usually signals strong Chinese demand, and a discount signals weaker demand. Gaps can last for weeks because China controls gold imports through licensed banks and restricts gold exports.
Physical Gold in Asia
The Shanghai Gold Exchange has made China the centre of the world’s physical gold trade. Every year, hundreds of tonnes of newly mined and imported gold move through its vaults, and very little of that gold comes back out. The SGE’s benchmark and the Shanghai-London premium are now standard signals for anyone following gold demand.
For individual investors outside China, though, the SGE is mostly something to watch rather than use. Only member institutions can trade on it, and China’s capital and gold export controls make it a hard place for foreigners to own metal.
Singapore offers a practical alternative within Asia. It has a stable legal system and a well-established precious metals trade, and investment-grade gold and silver are exempt from GST. Investors can buy gold in a wide range of bars and coins and take delivery. They can also keep their gold in vault storage in Singapore. There it is held as fully allocated metal in their own name, not as a claim on a pool.
Subscribe to Gold University Articles
Copyright Information: BullionStar permits you to copy and publicize articles or information from the BullionStar Gold University provided that a link to the article's URL or to https://bullionstar.com is included in your introduction of the article or blog post together with the name BullionStar. The link must be target="_blank" without re="nofollow". All other rights are reserved. BullionStar reserves the right to withdraw the permission to copy content for any or all websites at any time.